{May 2024} Moving Forward
After a difficult March and April, where 6 contracts didn’t get signed back to back, May offered a much needed respite from that string of heartbreak. We sent out another 5 contracts in May and only one fell out. What good fortune this month! The market still felt uncertain and choppy, with rates still high and the elections looming large. But on balance, the few buyers who were out there acted with more conviction.
We were marketing 8 listings for sale. The 1 listing that had a lot of activities and got multiple offers was a renovated studio condo in Midtown Manhattan under 600k. Buyers were very price driven in this market. The other listings were mostly quiet with 1-2 inquiries per week. The one thing that scared the buyers the most was high common charges. With high rates, buyers were hyper sensitive to high monthly charges. People also really didn’t want to do work. A renovated home would sell so much easier.
We did 5 buy-side deals in May: 4 were in new construction condos and 1 was a two-bedroom coop under 1mm. These buyers were very clear about what they wanted. Again, this was a market for strong buyers, buyers who knew what they wanted and were not easily pushed around by opinions around them.
Overall, inventory climbed higher in Manhattan: NYC now had 9 months of supply. This meant the city was over-supplied with a long-term average of 7.6 months. To put that into perspective, in 2019 we had the same level of supply. Supply built up over the pandemic to a high of 20 months and started to decline in Dec 2020. It reached a low of 5.5 months in May 2022, right before the rate increase. Inventory then rose over the next 2 years as rates went higher.
New Construction
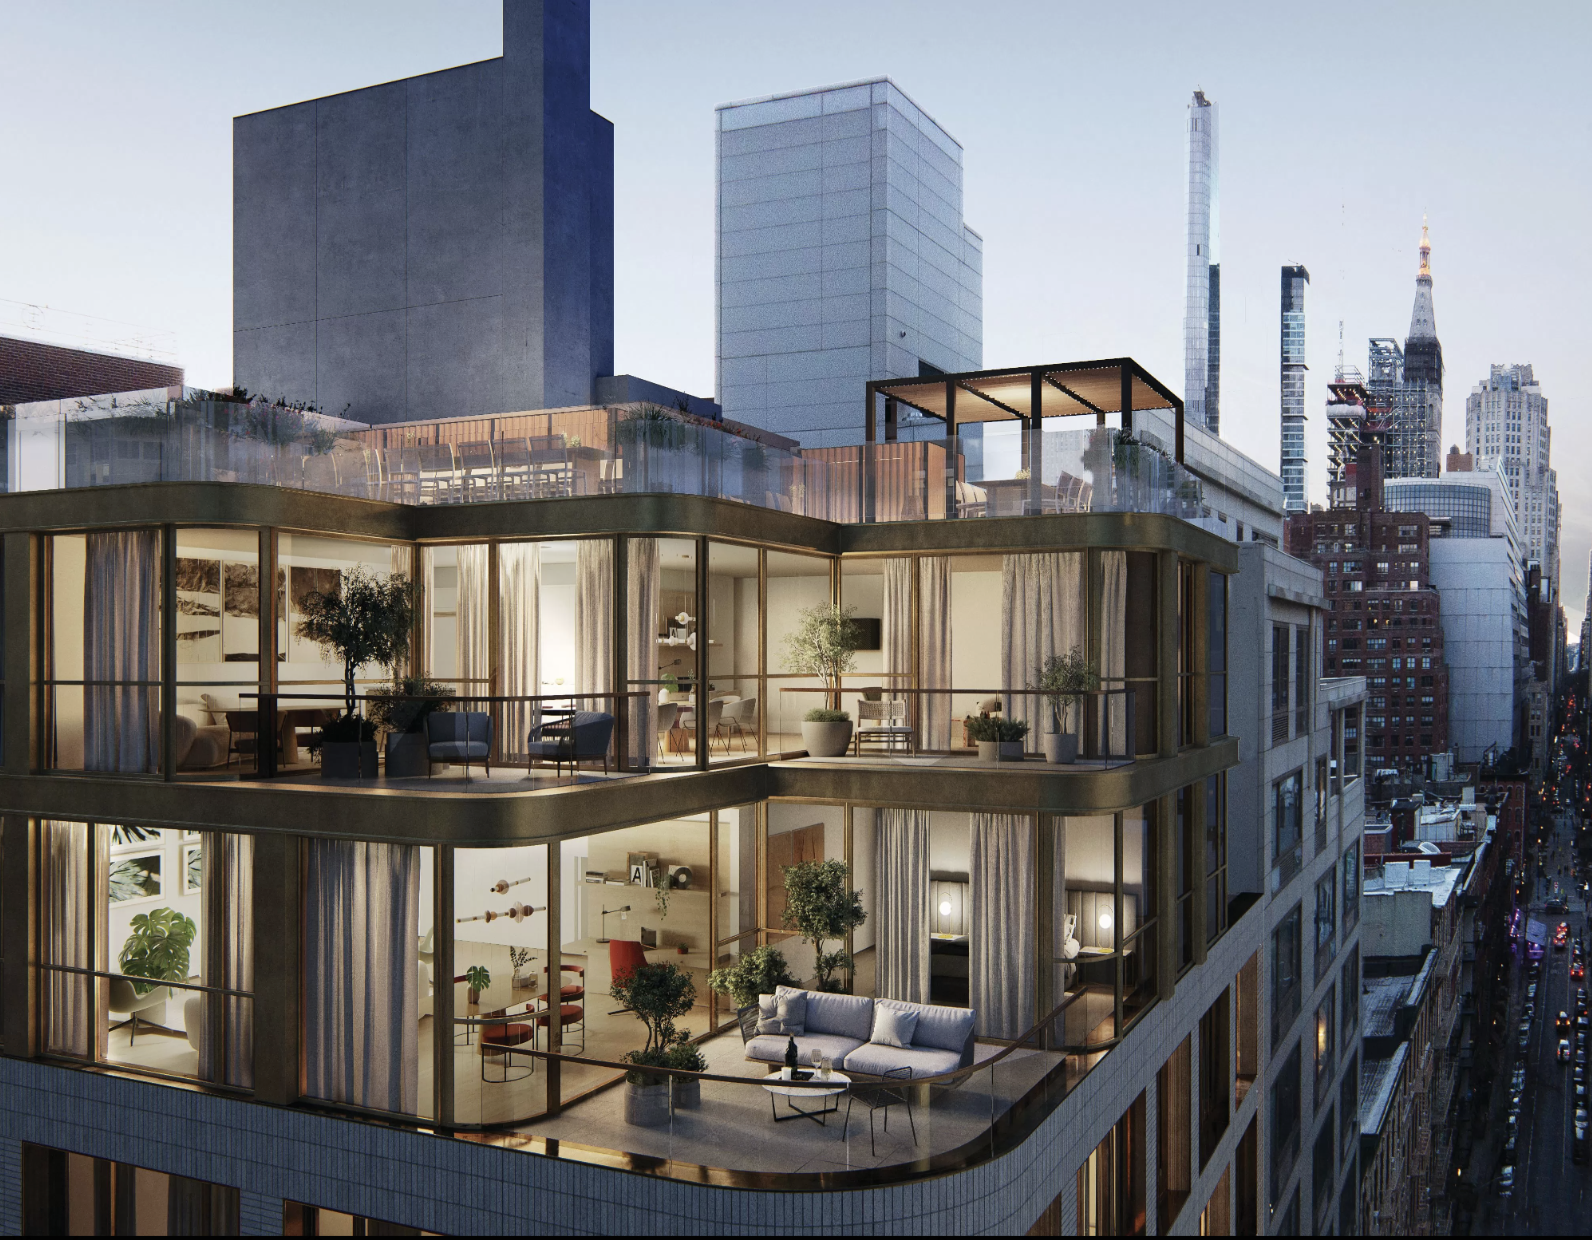
This month we would like to introduce The Hendrix House! The Hendrix House will be a new boutique condo in Kips Bay, a neighborhood that is getting a lot of attention from buyers for its convenient location and good value. Hendrix House will have 12 floors and 59 units.


So far, 2025 has been an interesting year. Transaction volume is higher than in 2024, yet the market doesn’t feel consistently busy—it ebbs and flows. I believe 2025 is a true inflection point.